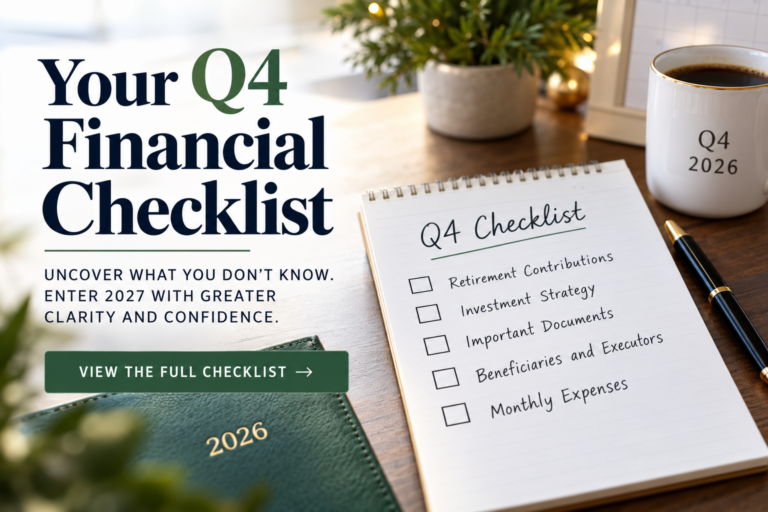
Your Q4 Financial Checklist: 5 Things You Should Know Before Year-End
“To know what you know and what you do not know, that is true knowledge.”
— Confucius1
This quarter’s checklist is all about increasing your knowledge…by examining what it is you know to find out what you do not know.
Your financial life is vast and complex. Almost everyone’s is, to a degree. There are so many things to keep track of. So many things that need doing. So many boxes to check, dates to remember, and bits of data to organize.
Our job is to handle as much of this for you as possible. However, it’s easy to sometimes realize:
I don’t know why I do X.
I don’t know whether I’ve done Y.
I’m not sure where to find Z.
Figuring out what you don’t know (and then taking steps to close those gaps) is one of the best ways to feel clarity about your financial present and confidence in your financial future. So, this quarter’s checklist is designed to help you bridge those gaps, if and where they exist. Some of the items may not apply to you; some you may be able to check off instantly. For any you can’t check off, let us know, and we can work together to fix it!
In the meantime, we wish you a great fourth quarter and a happy holiday season!
Q4 Financial Checklist for 2026 |
|---|
| Tip: Print this out and stick it on the fridge or somewhere else it will be seen. That way, you can check off the items one by one as you complete them! |
| ▢ I Know How Much I’m Contributing to My Retirement Accounts Many people treat retirement accounts — especially 401(k)s, but Roth and Traditional IRAs can apply here too — with a “set it and forget it” mindset. That means they often don’t know how much they are actually contributing each year. Are you contributing the maximum permissible amount? Are you contributing enough to take advantage of employer matching? Or to reach your retirement goals on time? If you can’t think of your number, or if you don’t know how to find out very quickly, it’s time to change that. ▢ I Know Exactly Why I’m Invested the Way I Am Notice the word “why” as opposed to “what” or “how.” While it’s always important to know what investments you own, the real knowledge here is why you own them. The philosophy behind your asset allocation. The thinking behind your level of risk. The tax consequences and implications for your income in retirement. Is it necessary to know every detail? No. But the more you truly understand the why, the greater your confidence and peace of mind can be during market ups and downs. The acid test: Can you explain your portfolio to someone else? If not, that suggests we can work on this. ▢ I Know Where Everything is Located The totality of your financial life is expressed in documents. (So, so many documents.) Tax forms and receipts. Quarterly statements. Deeds and titles. Wills, trust agreements, medical directives, power of attorney. All of them are important. Some tend to sit, unread, for months or years at a time. All may be required at a moment’s notice. Do you know where to find each one? Do you know the account logins and passwords for each? And does a loved one know, too, in case they ever need them on your behalf? Organization is an important part of financial success, so if you can’t recall where something is or how to access it, we’ll help you figure it out! ▢ I Know Who My Beneficiaries and Executors Are This one is less about remembering and more about doing. Have you actually decided on your beneficiaries? Have you officially designated them? Have you settled on an executor? Do you need more than one? Have you told them? Have you discussed their responsibilities and compensation? And have you reviewed all these people in the last few years to make sure they are still the right fit? If the answer to any of these questions is “No” or “I don’t know,” let’s address it. ▢ I Know How Much I Pay in [X] Each Month Let’s face it: The days of balancing a personal checkbook are pretty much over. Everything is online and often automated these days. That’s great for convenience, but it does insert a kind of distance between us and our money. As a result, it can be easy to let our cash flow become inefficient. To waste money on unnecessary expenses. To pile on debt. That’s why the final bit of knowledge to gain this quarter is exactly how much you are paying in the following areas: * Interest (on credit cards, personal loans, student loans, etc.) * Subscriptions * Fuel and energy * Insurance premiums * Fees, fines, and penalties When you know what you are paying in these areas, as opposed to simply paying them automatically, we can look for ways to optimize your monthly finances, sacrificing less on the short-term altar so that more can be reserved for the long. We can also look for alternatives that may potentially help you do more, get more, and save more. Let us know if we can help! |